Carbon accounting has moved from a voluntary sustainability exercise to a core compliance and business function. Regulations like the CSRD and CBAM now require companies to measure emissions across their entire value chain. But the number you report depends heavily on how you calculate it.
This guide explains what carbon accounting is, the standards behind it, and the three methods companies use: spend-based, activity-based, and hybrid. You'll also find guidance on choosing the right method and how IPOINT supports the full process.
Carbon Accounting Methods: Key Facts at a Glance
-
Three calculation methods: Companies calculate carbon accounting data mainly through the spend-based, activity-based, and hybrid methods.
-
Accuracy depends on data type: Spend-based estimates rely on financial data and industry averages, while activity-based data uses real physical quantities for higher precision.
-
Hybrid is the enterprise default: Most organizations combine both approaches, using activity data for material categories and spend-based estimates to fill remaining gaps.
-
Standards are converging: GHG Protocol and ISO announced plans in July 2026 to merge their corporate carbon accounting standards into one global framework.
-
Regulatory acceptance: CSRD and the Science Based Targets initiative (SBTi) both accept hybrid accounting, provided companies disclose their data quality mix.
What Is Carbon Accounting?
Carbon accounting is the process of measuring, recording, and reporting the greenhouse gas (GHG) emissions an organization or product generates. It works much like financial accounting, except it tracks CO₂-equivalent (CO₂e) emissions instead of currency, producing a GHG inventory instead of a balance sheet.
A robust carbon accounting system does more than generate a single number for a sustainability report. It identifies where emissions originate across your operations and value chain, and it supports Scope 1, 2, and 3 classification. It also creates the data foundation for carbon footprint tracking, emissions trading, and credible net-zero claims.
The accuracy of that inventory depends entirely on which calculation method you apply to convert activity or spend data into emissions figures. That choice, more than any single tool, determines how much you can trust and defend your numbers.
Carbon Accounting Standards: GHG Protocol, ISO 14064 & What's Changing
Carbon accounting rests on two main frameworks. The GHG Protocol, developed by the World Resources Institute and the World Business Council for Sustainable Development, sets the global standard for classifying and calculating emissions. The ISO 14000 family, specifically ISO 14064, provides a certifiable framework for organizational GHG inventories and third-party verification.
Both are evolving. GHG Protocol is revising its Scope 3 methodology for the first time since 2011, targeting a final standard around 2027. In July 2026, GHG Protocol and ISO also announced plans to merge into one global framework by 2027. Current guidance from both remains valid until that work concludes.
Companies operating in or trading with the EU also face mandatory disclosure under the Corporate Sustainability Reporting Directive (CSRD), which requires large in-scope companies to report material Scope 1, 2, and 3 emissions.
The Three Core Carbon Accounting Methods
The GHG Protocol's Technical Guidance for Calculating Scope 3 Emissions defines several ways to turn data into emissions figures. In practice, most companies build their carbon accounting methodology around three methods: spend-based, activity-based, and hybrid.
The Spend-Based Method
The spend-based method estimates emissions by multiplying what you spend in a category by an industry-average emission factor, typically drawn from environmentally extended input-output (EEIO) data. Spend $50,000 on packaging, apply the EEIO factor, and you get an estimate without collecting any activity data.
This method uses financial data you already have, making it the fastest way to build a first Scope 3 inventory. Because it ties emissions to price, results shift with inflation and currency, and the method cannot distinguish between suppliers with different environmental performance.
The Activity-Based Method
The activity-based method, known officially as the average-data method in GHG Protocol terms, replaces spend with physical quantities. You multiply a real amount, such as liters of fuel or kilowatt-hours of electricity, by an emission factor specific to that activity.
Multiply ten thousand liters of diesel by roughly 2.68 kg CO₂e per liter, and you get a far more precise result than estimating the same purchase from its price. Comparisons across categories like purchased services show spend-based estimates can overstate emissions by more than 30%.
The Hybrid Method
The hybrid method combines the other two: use activity-based or supplier-specific data for your most material emission categories, and fill remaining gaps with spend-based estimates. GHG Protocol guidance treats this hybrid approach as the practical default, since few organizations can source primary activity data for every supplier and purchase.
CSRD and SBTi both accept hybrid inventories. What they require is transparency: disclose which categories rely on primary versus secondary data, then improve that mix as supplier engagement matures.
| Method | Data Used | Emission Factor | Best For |
|---|---|---|---|
| Spend-based | Amount spent | Industry average (EEIO) | Fast baseline, low-priority categories |
| Activity-based | Physical quantity (kWh, kg, liters) | Activity-specific | Material categories, reduction planning |
| Hybrid | Combination of both | Mixed primary/secondary | Most enterprise CSRD/SBTi reporting |
The three carbon accounting methods compared by data input, emission factor, and typical use case.
How to Choose the Right Carbon Accounting Method
Choosing a method comes down to three questions: how material is the category to your total footprint, how much activity data you can collect, and which reporting standard to satisfy.
Start with spend-based estimates for low-materiality categories and your first Scope 3 inventory overall. This gives you a complete baseline that satisfies early CSRD Scope 3 and SBTi requirements. Then prioritize your highest-emission categories, often purchased and capital goods, for an upgrade to activity-based or supplier-specific data. The same data discipline behind Material Flow Cost Accounting (MFCA) pays off here: better underlying data produces more accurate emissions figures.
Document your data quality mix transparently as you improve it. That transparency, more than perfect precision on day one, is what regulators, investors, and customers reward.
From First Estimate to Audit-Ready Inventory
Spend-based, activity-based, and hybrid methods are not competing options. They are stages in the same journey toward a carbon inventory that can withstand regulatory, investor, and customer scrutiny.
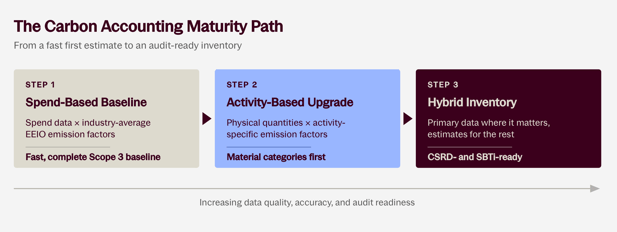
The carbon accounting maturity path: a spend-based baseline, an activity-based upgrade for material categories, and a hybrid inventory that balances effort against accuracy.
Most companies start with spend-based estimates, move activity data into their most material categories, and settle into a hybrid model that balances effort against accuracy. What matters most is transparency about where your data stands and a clear plan for improving it.
Turn Carbon Accounting Data Into Audit-Ready Reporting
Calculate Product and Corporate Carbon Footprints across Scope 1, 2, and 3 with IPOINT's software, aligned to GHG Protocol and ISO 14064.
Frequently Asked Questions
Why is carbon accounting important?
Carbon accounting provides the data foundation for climate commitments, from CSRD and CBAM to science-based targets. Without it, companies cannot identify emission hotspots or respond to investor and customer requests. It turns climate action into a measurable, auditable process.
What is the difference between the spend-based and activity-based methods?
The spend-based method multiplies purchase costs by an industry-average emission factor. The activity-based method multiplies physical quantities, like liters or kilowatt-hours, by an activity-specific factor. It's more accurate but takes more effort to collect, so most companies combine both.
Which carbon accounting method should my company start with?
Most companies start with the spend-based method because it uses financial data they already have. From there, prioritize your highest-emission categories, such as purchased goods, for an upgrade to activity-based data. A hybrid approach combining both is the realistic long-term target.
What is the most widely used carbon accounting standard?
The GHG Protocol is the most widely used carbon accounting standard worldwide, alongside the ISO 14064 series. In July 2026, GHG Protocol and ISO announced plans to merge these frameworks into one global standard by 2027. Both current standards remain valid until that revision is finalized.